Yield to Worst and How to Compare a Bond’s Redemption Scenarios
Calculate all eligible call and maturity yields, identify the binding scenario at two prices, and see why voluntary puts and default need separate treatment.
In this chapter
Intermediate
Yield to worst (YTW) is the lowest yield among the redemption scenarios included in the stated quote convention, assuming their payments are made. For a simple callable bond, that usually means comparing maturity with the eligible issuer-call paths.
The important work is deciding which paths belong in the comparison. “Worst” does not mean the lowest return under every possible event. Default, an early market sale and a poor reinvestment outcome can be worse than the quoted YTW.
Define the eligible set before taking a minimum
Our fictional Maple Instruments Inc. senior unsecured note has $1,000 face and $60 annual coupons. You acquire it on 1 January 2027, with zero accrued interest. Coupons fall on 1 January 2028, 2029 and 2030; maturity principal is due in 2030.
Its only issuer calls are immediately after the year-one coupon for $1,020 and immediately after the year-two coupon for $1,010. Assume valid 30–60 calendar days' notice for an exercised call. There is no continuous call, make-whole route, sinking fund, extraordinary redemption or other issuer option in this example.
The quote convention for this lesson includes exactly these three paths:
- First call in 2028 at $1,020.
- Second call in 2029 at $1,010.
- No call and repayment at maturity in 2030.
All yields are annual effective, calculated from full price with no fees or taxes and performance of the stated payments. This is a defined teaching convention, not a claim that every data provider includes the same features or annualises identically.
| Years from acquisition | First-call path (USD) | Second-call path (USD) | Maturity path (USD) |
|---|---|---|---|
| 1 | $1,080.00 | $60.00 | $60.00 |
| 2 | $0.00 | $1,070.00 | $60.00 |
| 3 | $0.00 | $0.00 | $1,060.00 |
Each call-date amount includes the $60 coupon plus that call's redemption. Every path begins with the same negative full purchase price at time zero.
Calculate the scenario yields
For each path \(j\), solve:
\[ P_{\mathrm{full}}=\sum_{t=1}^{n_j}\frac{CF_{j,t}}{(1+y_j)^t}, \qquad YTW=\min_{j\in\mathcal E}(y_j). \]
\(P_{\mathrm{full}}\) is purchase price in USD; \(CF_{j,t}\) is the USD payment in year \(t\) under scenario \(j\); \(n_j\) is that path's final year; \(y_j\) is its annual-effective payment IRR; and \(\mathcal E\) is the explicitly eligible scenario set. YTW uses the same annual basis for every rate being compared.
The YTM lesson explains the price-to-cash-flow equation. For calls, change the endpoint and redemption price rather than assuming the maturity payment still occurs.
Worked application 1. A premium purchase makes the first call binding
Pay $1,040. For the first call, there is one payment: \(1,040=1,080/(1+y_1)\), giving 3.846153846…%.
For the second call solve \(1,040=60/(1+y_2)+1,070/(1+y_2)^2\), giving 4.357678531…%. For maturity solve \(1,040=60/(1+y_M)+60/(1+y_M)^2+1,060/(1+y_M)^3\), giving 4.543707070…%.
| Eligible scenario | Annual-effective yield at $1,040 |
|---|---|
| First call | 3.8462% — binding YTW |
| Second call | 4.3577% |
| Maturity | 4.5437% |
“Binding” means this scenario supplies the minimum in the calculation. It does not mean the issuer is obliged to choose it. Here the early call leaves less time to earn coupons before the purchase premium is partly lost on redemption.
Worked application 2. A discount purchase changes the binding path
Keep the complete call schedule and all payments, but pay $960 instead.
The first call gives \(1,080/960-1=12.5\%\). The second-call equation has the same two inflows but a lower starting price, producing 8.745068918…%. The maturity equation produces 7.539246697…%.
| Eligible scenario | Annual-effective yield at $960 |
|---|---|
| First call | 12.5000% |
| Second call | 8.7451% |
| Maturity | 7.5392% — binding YTW |
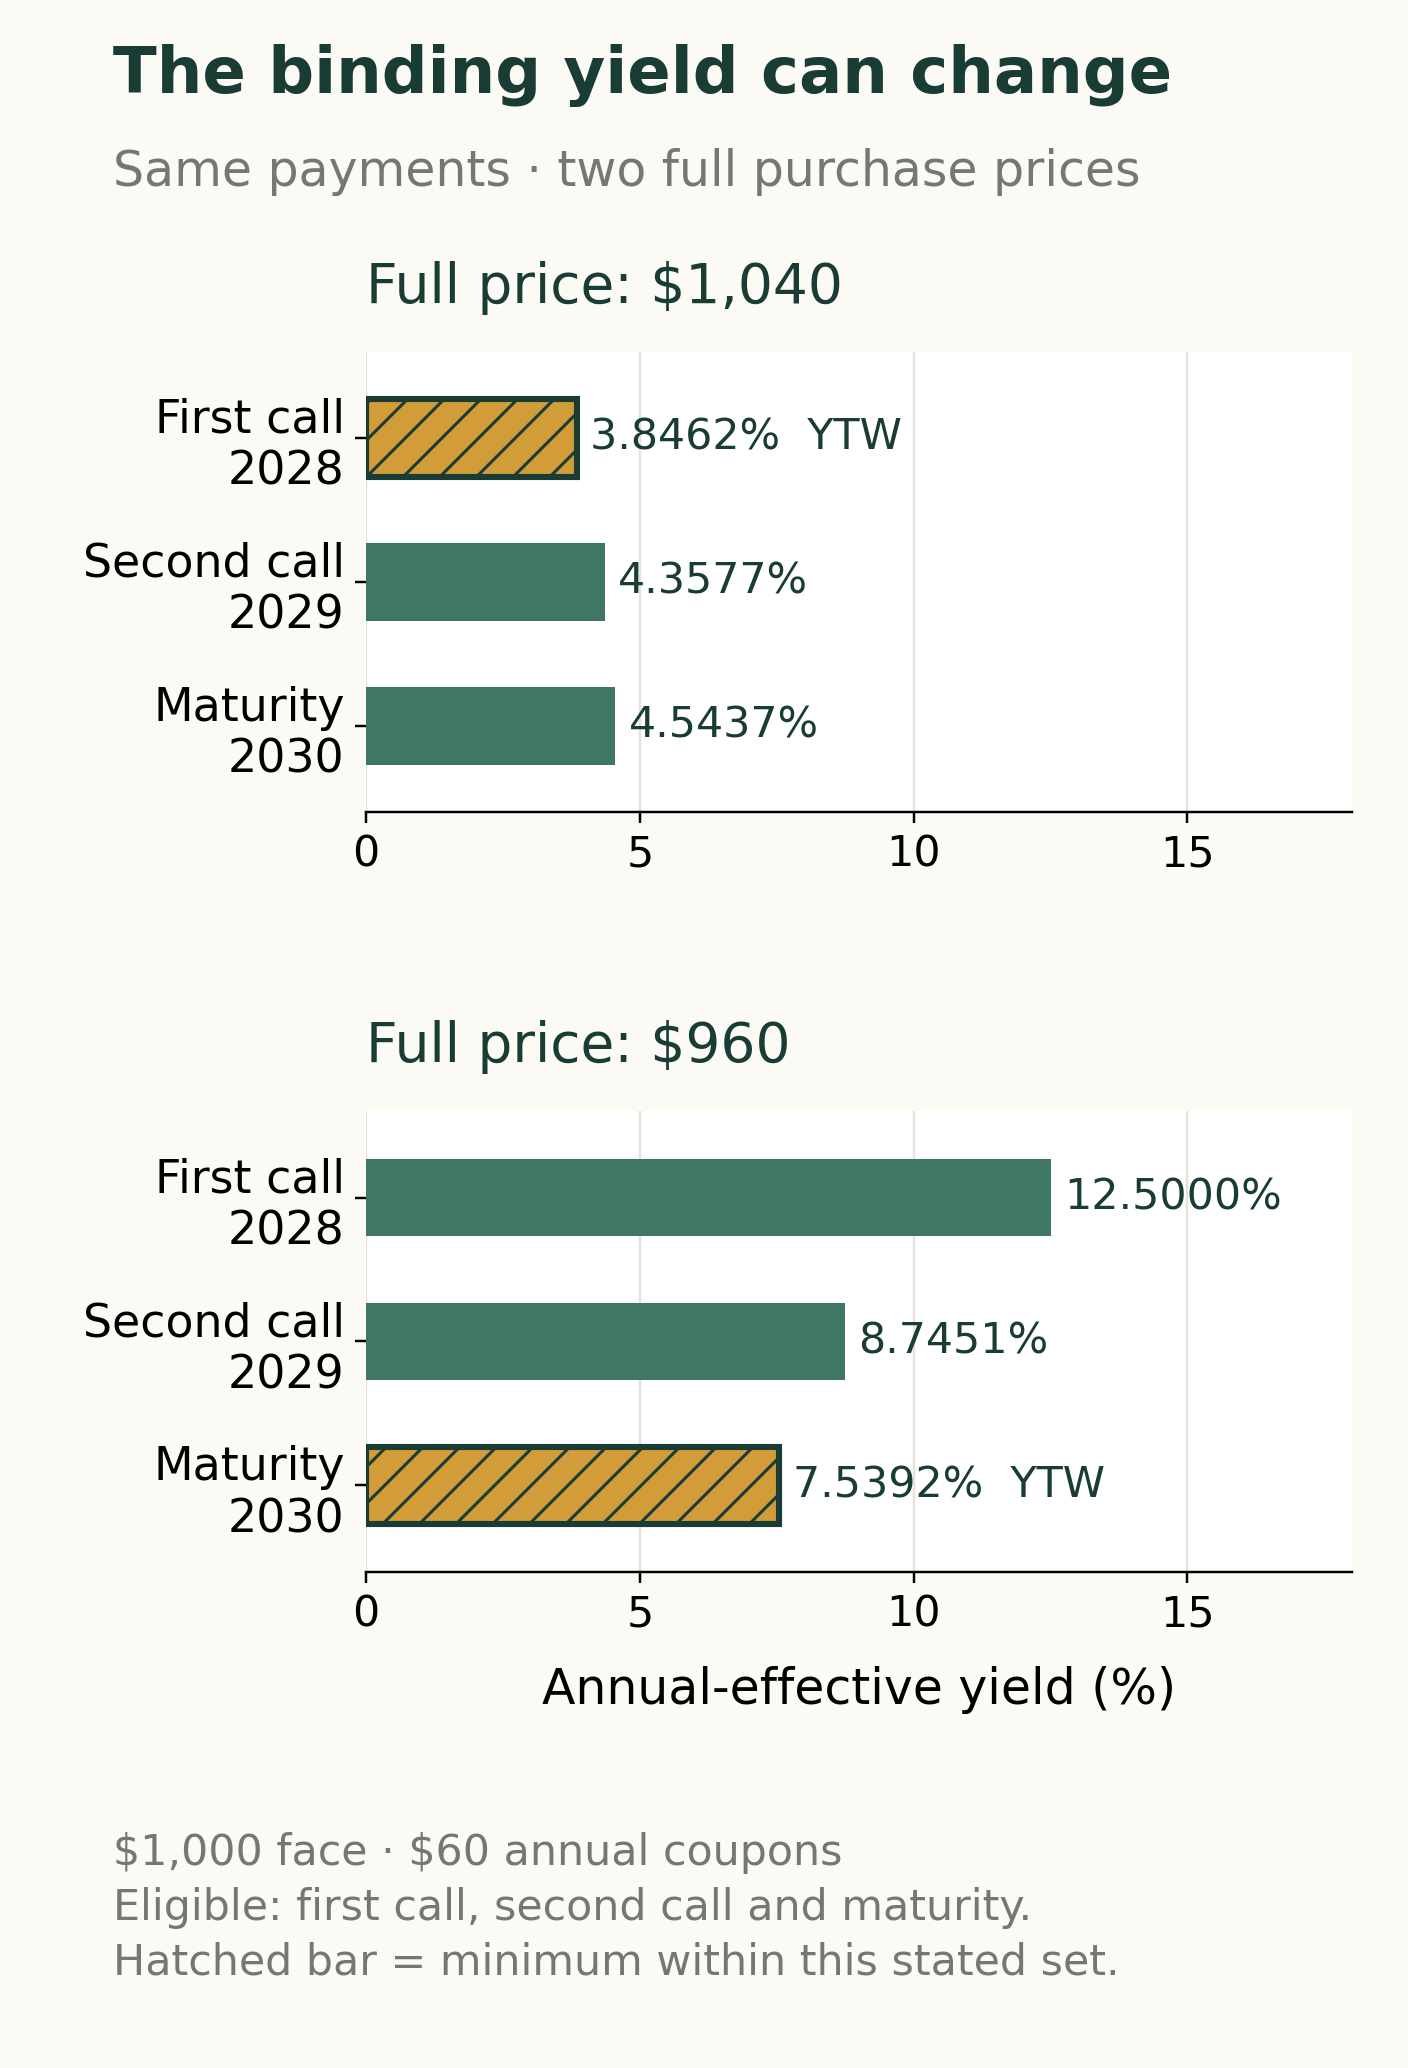
The discounted purchase benefits from getting principal and the call premium sooner. Spreading the discount gain over three years instead produces the lowest yield in this eligible set. Computing only first-call yield would therefore misstate YTW at $960.
Why a voluntary put is a different decision
Suppose a separate version of the note also gives its holder an optional put. That right belongs to the investor. A holder can decline an unattractive voluntary put, whereas it cannot refuse a valid issuer call that applies to its notes.
Under this lesson's quote convention, voluntary put yields are reported separately and are not mechanically added to \(\mathcal E\). Do not lower YTW merely because a holder could choose an inferior put path. For a different vendor's quote, check its method and which put or mandatory-redemption provisions it includes.
The put may nevertheless be valuable. If its exercise payment is better than continuing, the investor can compare and use it under its own terms. The exercise choice requires the current alternatives and notice rules, not just a historical purchase yield.
What YTW leaves outside its comparison
At the $1,040 purchase price, YTW is 3.8462% under the eligible promised-payment paths. If the issuer later pays only a $500 recovery, that outcome does not respect those assumed payments and can produce a loss. There is no contradiction: default was outside the eligible scenario set.
Interim coupons create a separate reinvestment question. If the no-call maturity path at $1,040 pays $60, $60 and $1,060, and the first two coupons earn zero afterward, terminal cash is $1,180. Its annualised wealth growth is about 4.2997%, rather than the 4.5437% payment IRR of that path. The IRR calculation still correctly describes its dated payments.
Before using a quoted YTW, record full price, settlement date, eligible redemptions, notice assumptions, coupon frequency and annual quotation. Then the number tells you something precise: the lowest payment yield within that named set.
Practice questions
Choose one answer per question. Use the stated contract, dates and rate convention. Hypothetical money amounts are USD; ignore fees and taxes unless stated. Round only the final displayed answer.